Post

Portability or a credit-shelter trust

Choosing between portability and a credit-shelter trust takes more than preserving an estate-tax exemption.

The right choice depends on future growth, income-tax basis and what the family needs from the assets.

This Daily Tax Planning Strategy compares portability and credit-shelter trust planning after the first death.
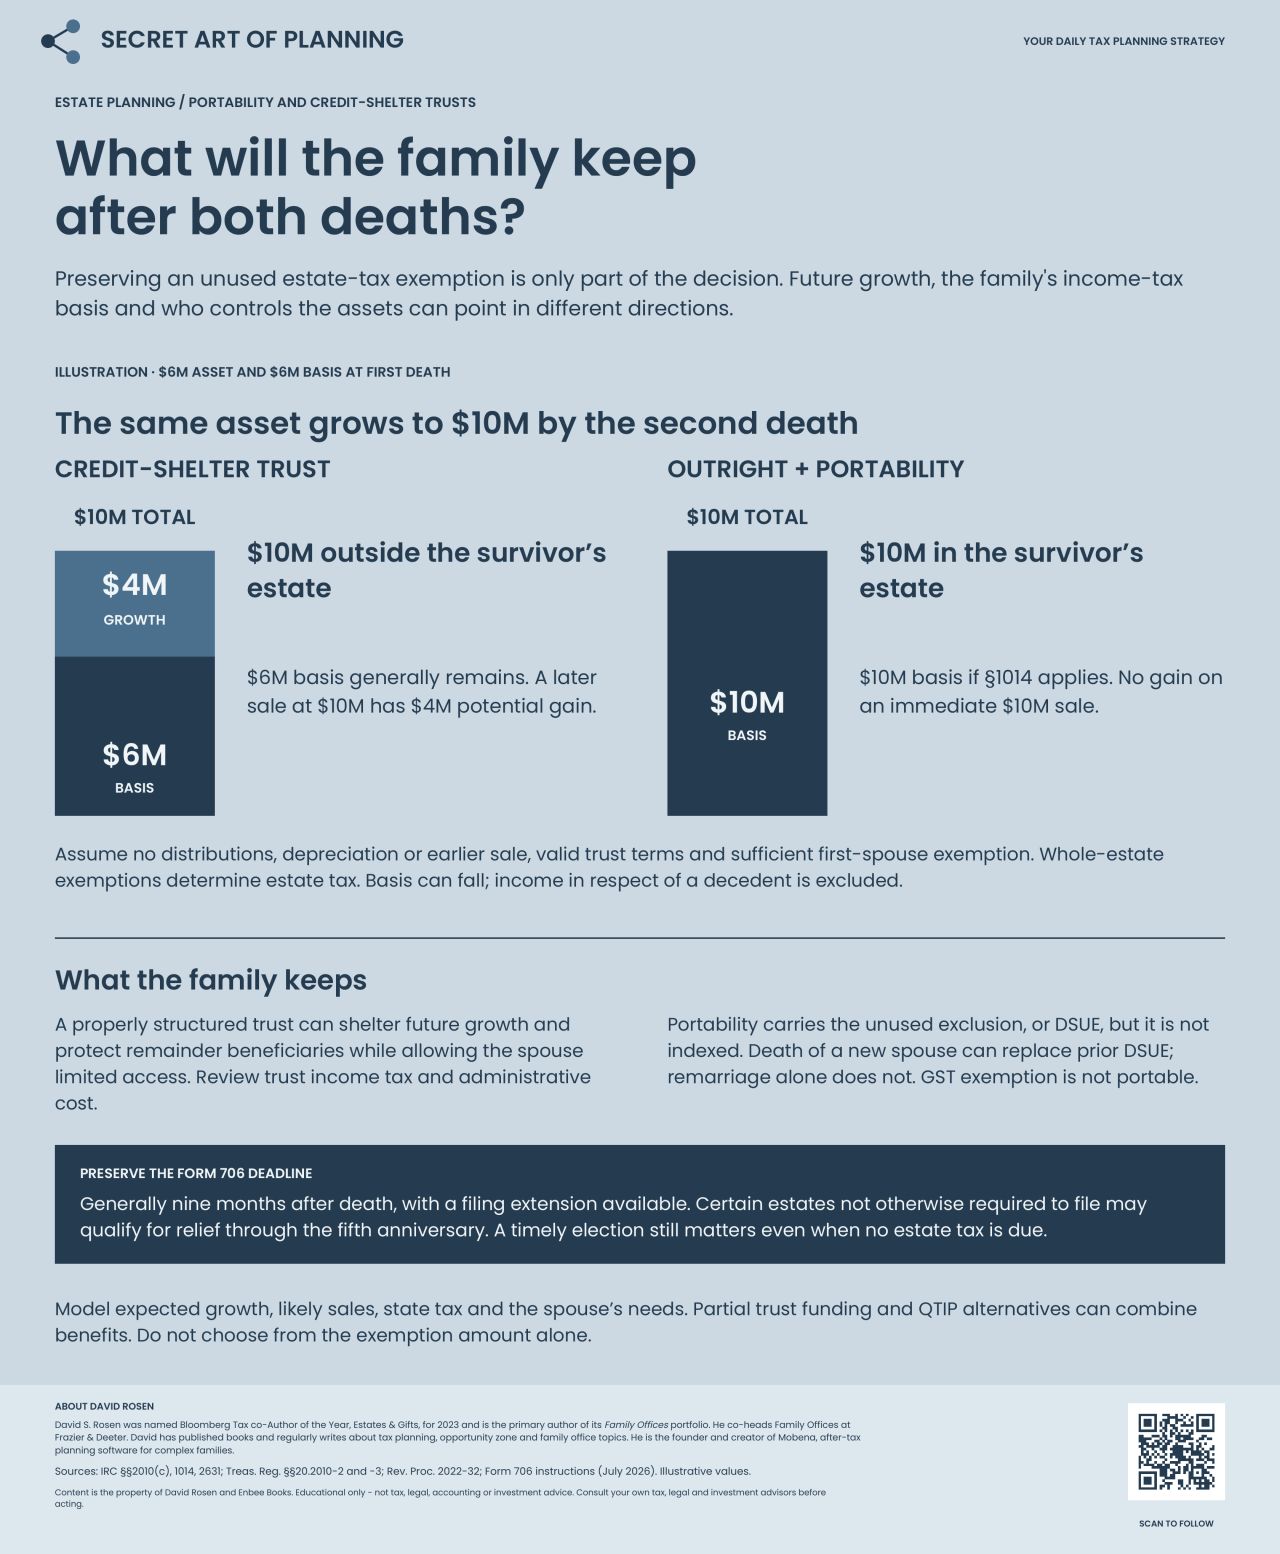
Two estate-planning lanes follow a $6 million asset with $6 million basis at the first spouse's death to $10 million at the second death. A properly structured credit-shelter trust can keep the $10 million outside the survivor's estate but generally retains $6 million basis. An outright transfer with portability includes $10 million in the survivor's estate and may obtain a $10 million basis under section1014. Notes explain DSUE, nonportable GST exemption, whole-estate modeling and Form706 deadlines.
Published with this post. Open full-size graphic ↗

View original post and attachments on LinkedIn ↗

Back to the archive →